

You can be halfway through selling a business in the GTA and still not know whether the next buyer is going to pay your asking price, chip away at it, or demand protections that make the cheque smaller than you expected. That’s where transaction advisory services matter. They are not a tidy-up exercise. They are the work of translating your numbers into the risks a buyer, lender, lawyer, or board will price into the deal.
For owner-managers, that difference is everything. A clean set of statements can still hide owner compensation, one-time expenses, related-party charges, customer concentration, and working-capital distortions that will come back in diligence. In Ontario, where deal activity is concentrated and private businesses are a big part of the market, that translation work has real consequences for price, structure, and closing conditions. Ontario led Canadian M&A activity in the latest quarterly reporting with 154 deals worth $22.9 billion in Q4 2025 (Crosbie & Company Canadian M&A Report for Q4 2025), and that kind of activity keeps pressure on advisors to do more than package the file.
What Owners Actually Mean When They Hear Transaction Advisory
The first time most owners hear the phrase, they think it means someone will “clean up the books” before a sale. That’s the wrong frame. A serious transaction advisory services mandate starts earlier and goes deeper, because the buyer isn’t paying for your bookkeeping habits. The buyer is paying for durable cash flow, defensible margins, and a risk profile they can live with.
What the owner thinks versus what the advisor does
An owner usually wants the file to look sale-ready. A transaction advisor wants the file to be decision-ready. That means taking reported results and converting them into a view a buyer can underwrite, which is very different from making the statements look neat.
Practical rule: if a number only works because the owner knows the backstory, it’s not yet transaction-ready.
That’s why owners get surprised when diligence starts asking about owner perks, related companies, unusual accruals, or why revenue in one month looks out of step with the rest of the year. The advisor isn’t being difficult. They’re testing whether the business can survive buyer scrutiny without the owner standing beside every line item.
The strongest engagements in the GTA do not treat TAS as a cosmetic pass over the numbers. They treat it as a way to turn accounting output into negotiation strength. That is the core job, and it’s why buyers, sellers, lenders, and counsel lean on the same financial picture but read it differently.
The Core Workstreams of a Transaction Advisory Engagement
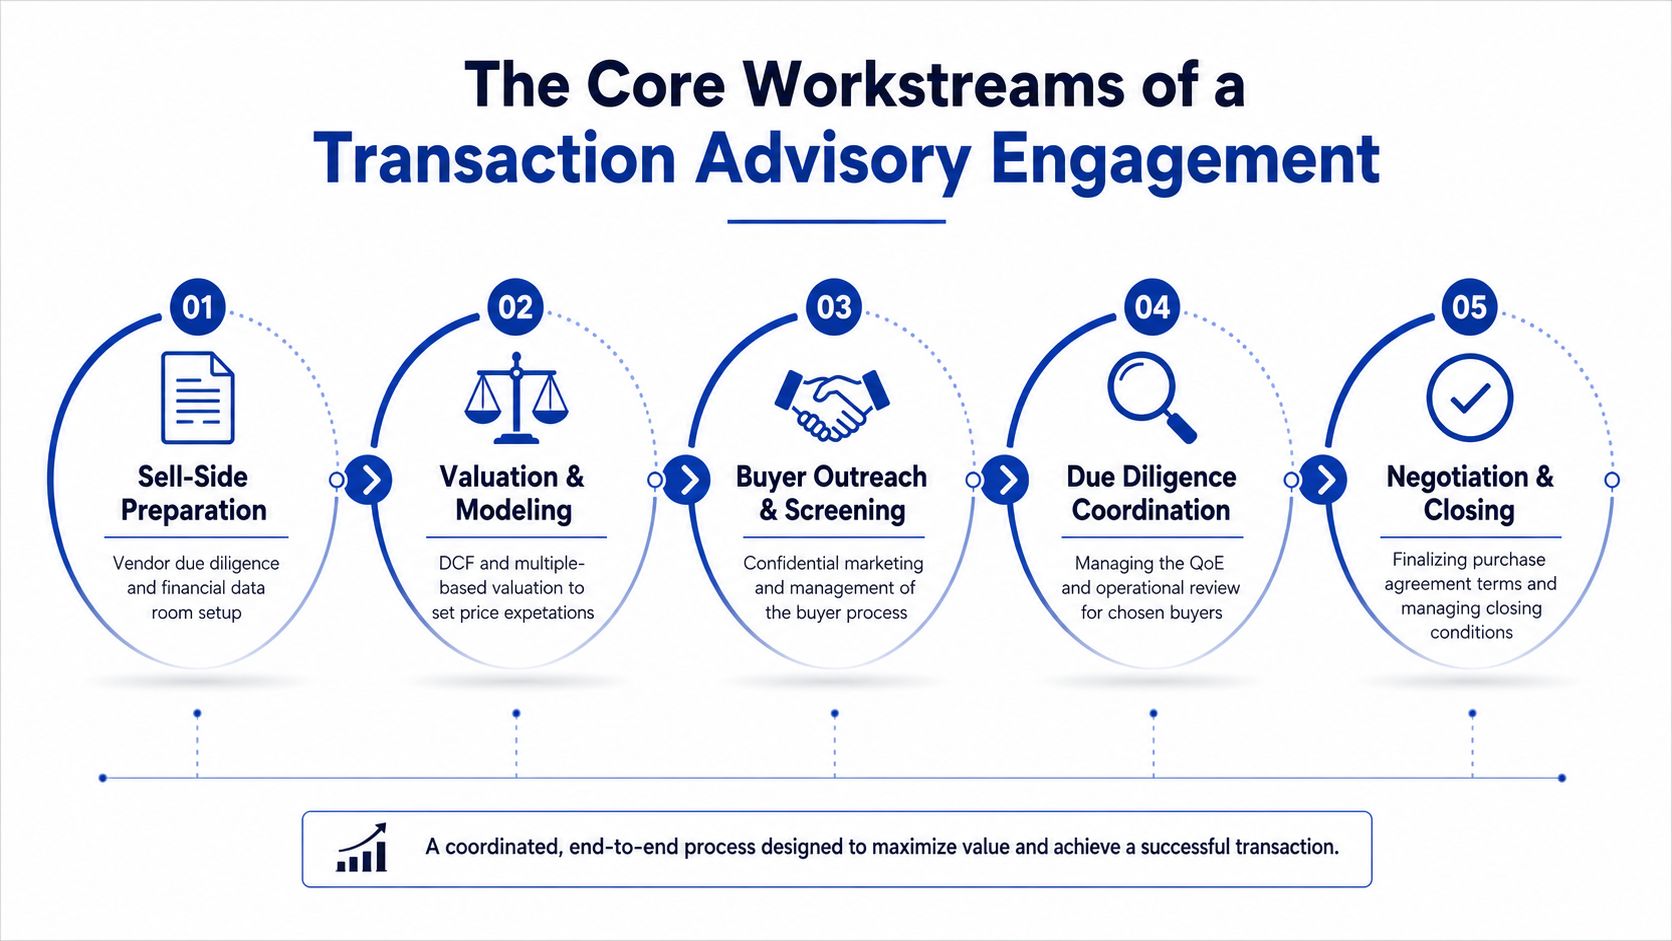
A private-company transaction rarely turns on one analysis. It turns on a sequence of linked workstreams, each one feeding the next. If you separate them too aggressively, contradictions show up late and cost money. https://www.youtube.com/embed/_PumGJEnAFA
Sell-side and buy-side work are not mirror images
On the sell side, the advisor helps prepare vendor diligence, package financial data, and support the management presentation so the business can be explained clearly and consistently. On the buy side, the advisor is there to challenge the seller’s story, test the numbers, and identify what the buyer is really taking on. Same financials, different objective.
Valuation and tax sit in the middle
Valuation support establishes where the business might reasonably trade, using market evidence and internal cash flow analysis. Tax structuring then asks the harder question, what does that price mean after the deal is documented and paid? A share sale, asset sale, rollover, or earn-out can leave very different cash in the owner’s hands.
The final workstream is the one owners underestimate
Negotiation and closing support is where the advisor helps connect diligence findings to the purchase agreement, indemnities, escrow, and post-close true-ups. That’s not admin. That’s where the deal becomes real.
The point is simple. Transaction advisory services are not one service, they’re a chain of decisions. If one link is weak, the buyer notices.
| Common Quality of Earnings Normalizations | Typical Treatment | Why It Matters |
|---|---|---|
| Owner compensation | Adjust to market or maintainable level | Prevents overstating recurring earnings |
| Personal expenses through the company | Remove from EBITDA | Stops non-business spend from inflating value |
| Non-recurring legal and professional fees | Exclude if truly one-time | Separates sale noise from operating performance |
| Related-party charges | Test whether they reflect market terms | Avoids hidden transfer pricing problems |
| Working-capital distortions | Normalise seasonal or unusual balances | Helps set a defensible closing target |
For readers who want to pressure-test how those numbers read in the financial statements, the discussion at C&P Partners on what financial statements are really telling you is a useful starting point.
Financial Due Diligence and Quality of Earnings in Practice
Financial due diligence is not a tour through the general ledger. It is a test of whether the earnings being sold are repeatable, supportable, and free of owner-specific distortion. In private-company deals, that matters more than almost anything else because the buyer is often underwriting future cash flow off a business that has never had to explain itself this hard before.
What the analyst is really checking
A proper quality of earnings review asks whether reported EBITDA reflects the business buyers can own after closing. That means looking at revenue recognition, margin stability, customer concentration, working-capital seasonality, and the treatment of unusual expenses. It also means testing whether add-backs are real or just hopeful.
Buyers don’t pay for optimistic normalizations. They pay for numbers they can defend to their own committee, lender, or fund.
In owner-managed businesses, the same few items usually move the number. Owner compensation gets reset to a market or maintainable level. Personal expenses get removed. Related-party charges get examined. One-time legal and advisory fees need a real explanation before anyone accepts them as non-recurring. If those adjustments are sloppy, the buyer’s negotiating power increases immediately.
A useful way to think about this is that diligence isn’t only about uncovering problems. It’s about making sure the purchase price, earn-out, working-capital target, and indemnity package are built on the right earnings base. If the buyer sees an overstated EBITDA, the discussion shifts fast, from valuation to protection.
Common Quality of Earnings Normalizations
| Normalization Item | Typical Treatment | Why It Matters |
|---|---|---|
| Owner salary above market | Reduce to a maintainable level | Prevents artificial EBITDA inflation |
| Personal vehicle, travel, or meals | Remove if clearly non-business | Keeps buyer underwriting clean |
| One-time legal work | Exclude when genuinely transaction-related | Avoids overstating recurring margin |
| Family payroll anomalies | Recast to arm’s-length economics | Clarifies true labour cost |
| Unusual accruals or reversals | Test before accepting | Stops balance-sheet noise from distorting earnings |
The broader diligence point is this. A buyer who receives this work before the letter of intent has more room to negotiate structure. A buyer who receives it later is usually negotiating after the price has already hardened.
Valuation, Tax Structuring, and Fairness Support
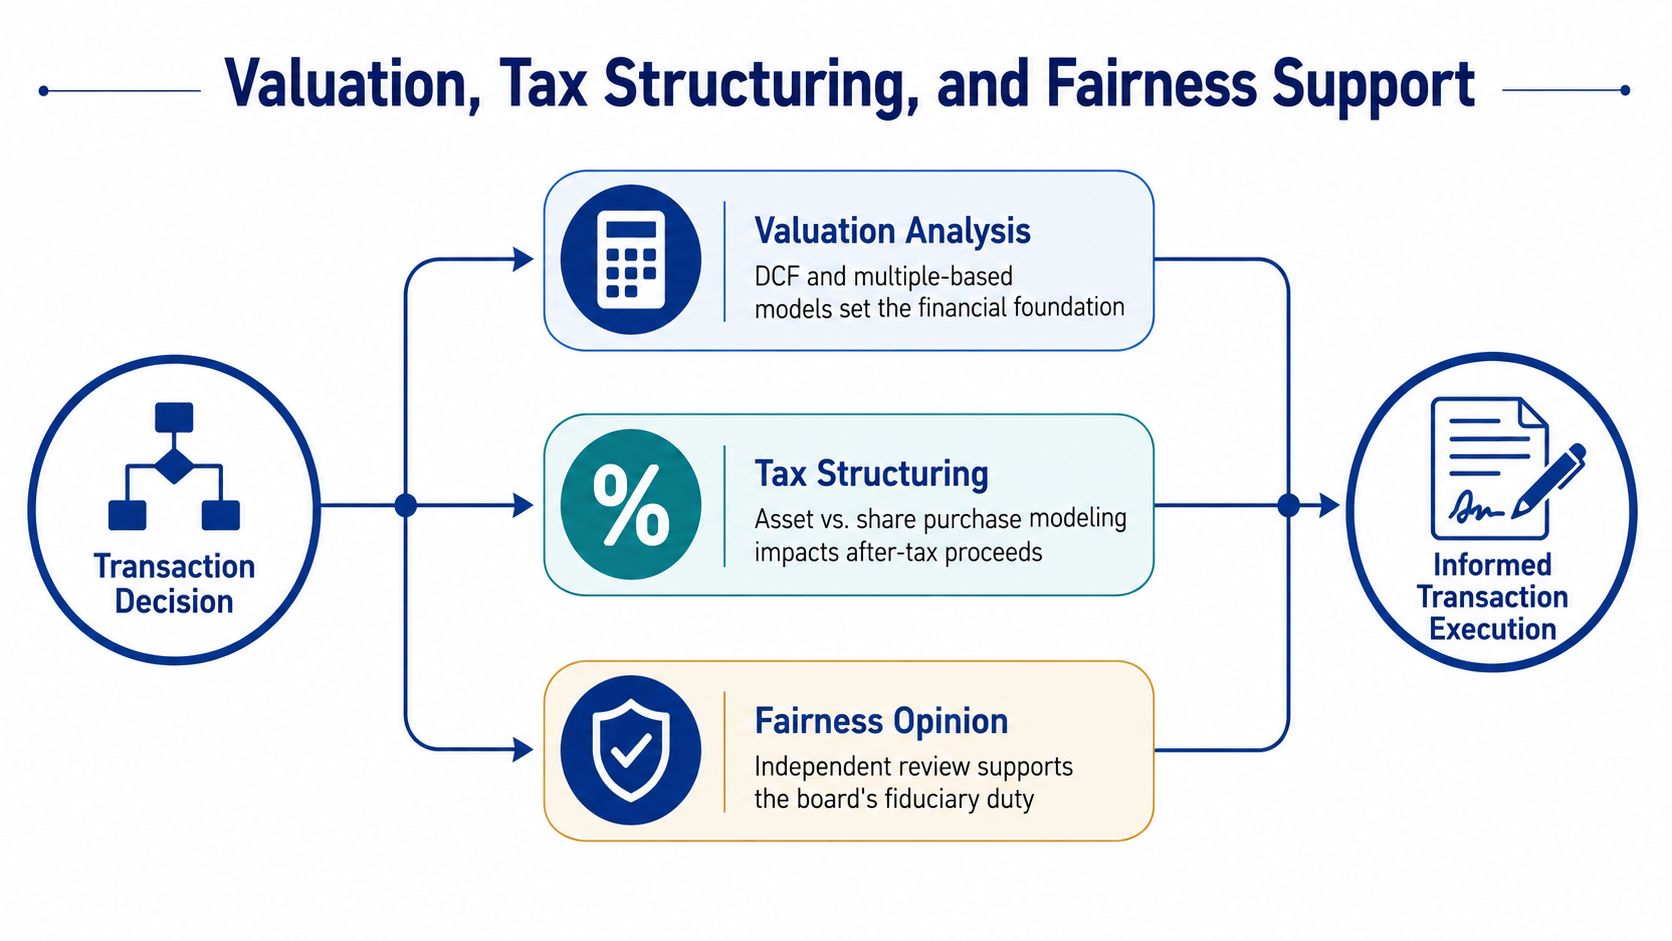
Valuation, tax structuring, and fairness support belong in the same conversation because they all affect the same outcome, what the owner keeps and what the deal can survive under scrutiny. Too many sellers treat them as separate technical boxes. That’s a mistake.
Start with the value range, then work backwards
A valuation sets the price expectations, not just the bragging rights. Whether the advisor uses a DCF-style framework, market multiples, or both, the result gives the owner a working floor and ceiling. The tax structuring work then asks how that value should be documented so the after-tax result matches the commercial deal as closely as possible.
In a private-company sale, the structure often matters as much as the headline price. Asset versus share sale treatment, rollover mechanics, earn-out design, and election planning can change the net outcome enough that two offers with the same gross number are not really the same deal. That’s why the sequencing matters. Valuation first, structure second, opinion support third.
Fairness support has a different job
A fairness opinion is not the same thing as a sell-side valuation. It is an independent review used where directors, minority shareholders, or other stakeholders need support for the view that the transaction is fair from a fiduciary perspective. The advisor providing it has to stay separate enough from deal advocacy to preserve credibility.
The best files keep these threads aligned from day one. If the valuation assumptions, tax elections, and fairness conclusion don’t fit together, buyer counsel and lender counsel will pick that apart quickly. A senior CPA’s value here is less about producing one document and more about keeping the logic coherent across all three.
For owners in Milton and the GTA looking for formal valuation capability, C&P Partners CPA’s business valuation services sit naturally alongside transaction work when the question is price, structure, or support for a shareholder decision.
Sell-Side Versus Buy-Side Support for Owner-Managers
Sell-side support and buy-side support overlap, but they do not serve the same master. The seller wants to protect value and reduce friction. The buyer wants to verify the story and expose hidden risk. That tension is built into the mandate.
Where the work overlaps
Both sides need comparable transaction analysis, market multiples, and a disciplined read on what the financials are saying. Both sides also need someone who understands how working capital, debt-like items, and unusual expenses affect enterprise value. That shared ground is why the same data room can support opposite conclusions.
Where the incentives diverge
On the sell side, the advisor helps get the business ready, frames the narrative, and tries to minimise avoidable buyer objections. On the buy side, the advisor is looking for revenue concentration, contingent liabilities, poor controls, and gaps between reported and maintainable earnings. One side is trying to reduce friction, the other is trying to surface it.
| Workstream | Sell-Side Focus | Buy-Side Focus |
|---|---|---|
| Earnings analysis | Present adjusted EBITDA clearly | Challenge every normalization |
| Working capital | Defend a fair closing baseline | Find leakage and seasonal traps |
| Deal support | Prepare management materials and data room | Verify claims and test assumptions |
| Tax matters | Clean up structure before marketing | Spot tax exposures and hidden cost |
| Negotiation input | Protect value and certainty | Reduce exposure and improve protections |
The practical lesson for owners is blunt. You can’t get both outcomes from the same advisor in the same role without creating confusion. Engagement clarity matters because loyalty and access define what the work can credibly deliver.
How Diligence Findings Move Price, Structure, and Protection
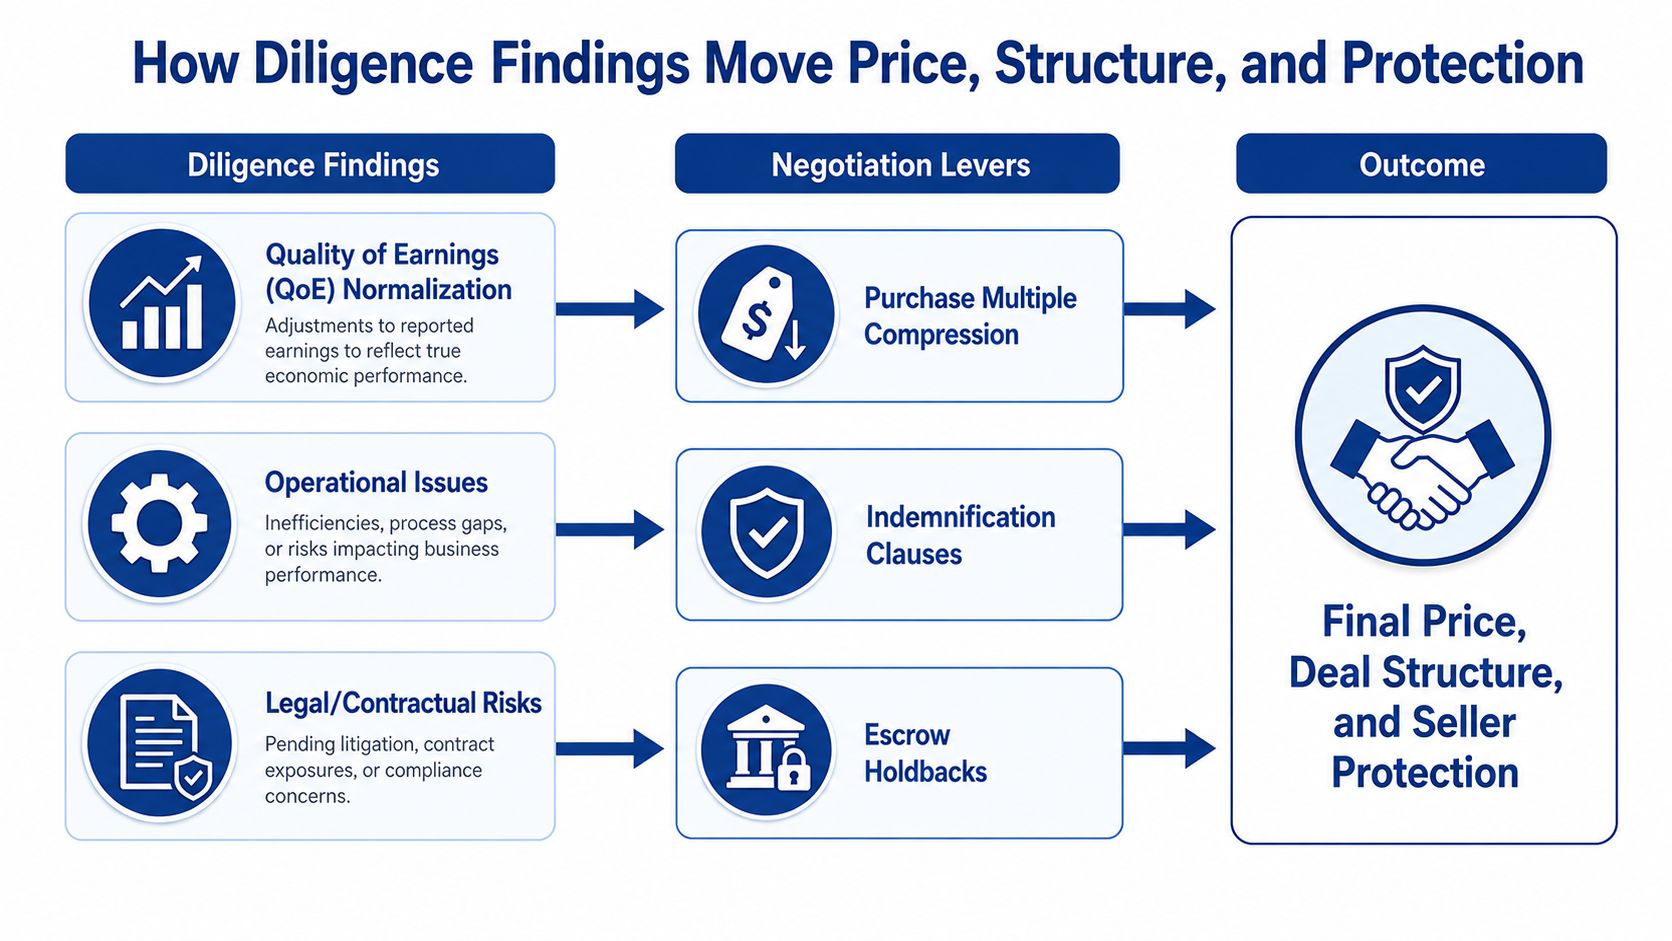
Owners either save or lose real money. Diligence findings are not just observations. They have to be translated into a dollar impact or a contractual protection. If nobody does that translation, the report is just expensive reading material.
Each finding should hit a deal lever
A QoE normalization that lowers EBITDA should compress the purchase multiple or reduce the enterprise value. A working-capital issue should move into the closing adjustment mechanism. A contingent liability should become a specific indemnity or be carved into escrow. An undisclosed customer risk may alter representation language or increase the buyer’s appetite for insurance.
That is what I mean by risk translation. The report is not done when the problem is named. It is done when the consequence is placed into the SPA, the closing statement, or the pricing model.
The seller’s job is to force clarity early
Owners lose negotiating power when they let diligence findings sit in the abstract. If the buyer says there’s a risk, the response has to be, what does that change in price, structure, or protection? The longer that answer stays fuzzy, the more likely it is the buyer will use the issue as a broad negotiating chip.
The market is already moving in that direction. Canadian deal commentary in 2025 pointed to longer, deeper diligence, more buyer-friendly protections, and wider use of representation and warranty insurance, while deal timelines in some mid-market transactions were stretching past 120 days (Kroll Canadian M&A Industry Insights Winter 2025). That means owners need to answer the risk question early, not after the purchase agreement is half-written.
Common Misconceptions and Why Senior CPA Involvement Matters
The biggest mistake I see is treating transaction advisory as if it only starts once the LOI lands on the desk. By then, a lot of the negotiating power is already gone. The better move is to have the financial story, tax exposures, and structural issues mapped before anyone starts anchoring on a headline number.
Three misconceptions that keep costing owners
First, clean financial statements are not the same thing as transaction-ready numbers. Second, a generic auditor is not automatically the right person to defend normalisations in a sale process. Third, the advisor is not just for the final stretch. They matter most when the owner still has room to shape the process.
Direct advice: if your advisor can’t explain how a diligence finding changes the SPA, the escrow, or the closing statement, you’re paying for commentary, not transaction support.
Senior CPA involvement changes the file because the issues that move price and protection are financial in nature. An experienced practitioner can spot the add-backs that won’t survive buyer review, the tax elections that create friction, and the balance-sheet items that will get recast as debt-like. That’s not theory. It’s the work.
For owners, the value is cumulative. A stronger valuation conversation makes the tax conversation cleaner. A cleaner tax structure makes closing smoother. A smoother closing reduces the room a buyer has to reopen the commercial debate.
Preparing for a Transaction Before the Letter of Intent
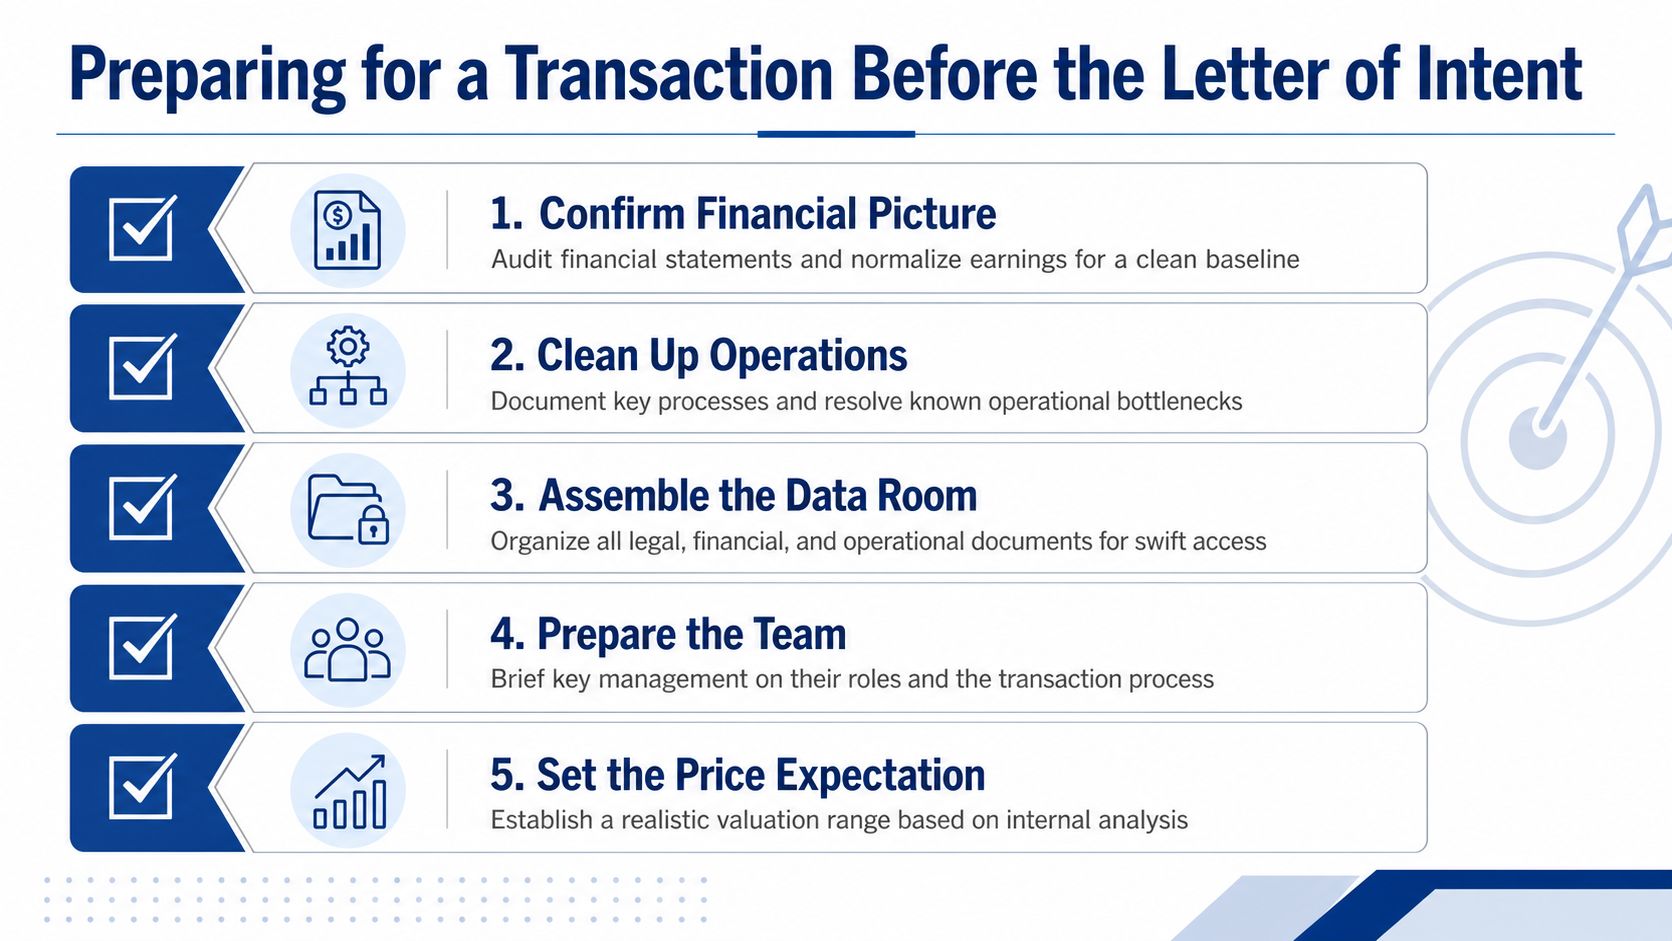
The best time to prepare is before a buyer has power over your calendar. That’s when you still control the story, the data room, and the order of fixes. Once the LOI is signed, everything gets harder and faster.
What to get right first
Start with the financial picture. Revenue recognition, owner compensation add-backs, working-capital normalisation, and one-time expenses need to be defensible, not exaggerated. Then clean up the cap table, option grants, and shareholder agreements so the structure doesn’t block the deal later.
After that, address tax exposures, intercompany balances, and prior-year filings that diligence will expose anyway. Build the management story around what the business does well, not what a seller hopes a buyer won’t question. Then decide who belongs on the deal team.
- Confirm Financial Picture: make sure the numbers can withstand buyer scrutiny.
- Clean Up Operations: remove obvious bottlenecks and document the key processes.
- Assemble the Data Room: keep legal, financial, and operational documents ready.
- Prepare the Team: brief management on their role and how buyer questions will be handled.
- Set the Price Expectation: agree on a realistic range before anyone anchors the conversation.
A deliberate pre-LOI process doesn’t guarantee a perfect sale. It does reduce surprise, and surprise is expensive in a transaction. If you’re planning a sale, recapitalisation, or ownership transition in the GTA, C&P Partners CPA can help connect the accounting, tax, and deal work so the numbers support the decision instead of hiding it. Visit C&P Partners CPA to start a conversation about transaction advisory services, valuation, and buy or sell support before the market starts negotiating for you.