
Tax planning services are advisory work that connect day-to-day accounting to the key decisions an owner or family is facing, not a year-end exercise in chasing deductions. In Canada, that matters because more than 32.9 million individual income tax and benefit returns were filed in 2023 to 24, and 92% were filed digitally, while about 2.9 million corporation income tax returns were filed with 94% filed digitally, which shows how tax work has moved into a year-round, software-enabled process where timing and structure matter before deadlines hit (CRA 2023 to 24 reporting). If you wait until filing season, you’ve already surrendered the decision.
Most owners still buy something much thinner than true planning. They get compliance, a few timing suggestions, and maybe a late November phone call about whether to pay themselves salary or dividend. That’s not the same thing as modelling what happens to the corporation, the owner, and the family balance sheet together.
What Tax Planning Services Are
Tax planning services start with the next decision, then work backward to the tax result. For an owner-manager, the question is not what can be deducted. It is what structure gives the best after-tax outcome for the move you are about to make.
Planning comes before the filing
Good tax planning is decision support. It should test compensation, retained earnings, share structure, family ownership, and exit timing before those choices are fixed in place. Ontario makes that especially practical right now, because the personal top marginal rate is 53.53% in 2026 and the small-business corporate rate is being reduced from 3.2% to 2.2% effective July 1, 2026 (CRA current-year brackets, Ontario budget 2026 coverage). That mix changes the answer depending on where income sits and when cash comes out.
A solid advisor should show the trade-offs between salary, dividends, retained corporate earnings, and longer-term ownership planning. If the discussion stops at a late-year guess about what to pay yourself, you are not buying planning. You are buying hindsight with a fee attached.
Practical rule: if the advice arrives after the decision is already made, it is compliance with commentary, not planning.
The work should be decision-ready
Real tax planning services are built around judgment calls. Should you incorporate a holding company? Should future growth sit in a freeze? Should you pull cash out now or leave it inside the corporation? Should you crystallize a gain before a transaction window closes?
Those questions are concrete. They affect how income is taxed now, how cash moves later, and how much flexibility you keep if the business, family, or rules change. In Ontario, that flexibility matters more because the small-business rate is being trimmed while higher personal income still faces a steep rate.
The firm should leave you with a recommendation, not a stack of scenarios. If you do not get assumptions, sensitivity points, and a clear explanation of what would change the conclusion, the engagement is too shallow.
The Core Areas a Tax Planning Engagement Covers
Serious tax planning isn’t one service with a few add-ons. It usually breaks into four buckets, and if your file isn’t touching all four, it’s incomplete.
Compensation and remuneration strategy
Salary, dividends, RRSP room, personal cash needs, and corporate cash retention often present competing priorities. A competent advisor won’t treat salary versus dividend as a slogan. They’ll map the owner’s personal spending, the company’s cash position, and the effect on future flexibility.
Corporate structuring
This bucket covers holding companies, family trusts, estate freezes, reorganisations, and capital gains planning. It becomes especially relevant when you’re thinking about future sale proceeds, intergenerational transfers, or how to separate risky operating assets from longer-term wealth.
Family income and attribution issues
If a spouse or adult child is involved, the planning has to deal with income sprinkling, attribution, and TOSI. That isn’t about “making family members shareholders” and hoping for the best. It’s about whether there’s real involvement, fair consideration, and a defensible structure.
Transactions and transition events
The stakes rise when planning taxes for share sales, business succession, emigration, immigration, and estate events. All need deliberate sequencing. Once the deal is signed or the estate event is underway, your options narrow fast.
The deliverable should be more than a memo that says “consider these strategies.” It should say what to do, what not to do, and why.
| Planning Area | Key Decisions Addressed |
|---|---|
| Compensation and remuneration strategy | Salary versus dividends, personal cash flow, RRSP room, corporate retention |
| Corporate structuring | Holdco use, estate freeze, family trust, sale-readiness |
| Family income and attribution issues | Income sprinkling, TOSI exposure, spouse or adult child involvement |
| Transactions and transition events | Sale timing, succession, immigration or emigration, estate sequencing |
Why Personal and Corporate Planning Must Run Together
A 50-year-old Ontario owner-manager taking $250,000 personally and holding $1.5 million inside the corporation is already in two tax systems at once. Add a partial share sale in three to five years, and the problem is clear: firms that treat the personal return and the corporate return as separate files miss the core decision.
A siloed approach optimises the wrong thing first. An advisor may push salary or dividend in isolation, leave excess investment assets parked in the operating company, and wait until the letter of intent arrives before raising freeze mechanics. By then, the structure has already narrowed the options.
A coordinated approach does the opposite. It lines up compensation with the owner’s personal cash needs without giving away corporate flexibility. It shifts future growth into the right ownership bucket early. It also leaves room to receive sale proceeds in a cleaner structure instead of scrambling when the deal is nearly done.
Ontario’s 2026 rules make that coordination harder to ignore. The Ontario Ministry of Finance budget summary and related budget coverage show why corporate retention, passive income, and owner compensation have to be modelled together before the decision is made.
That is the standard a planning-led firm should meet. The corporation, the spouse, and the exit should be tested as one combined scenario. If you want a practical example of how corporate planning can be built around the owner’s bigger decision set, look at corporate tax planning in Milton.
If the corporation, the spouse, and the exit are being discussed by different people at different times, you are paying for fragments, not strategy.
Compensation, Passive Income, and the 2026 Ontario Reality
The salary versus dividend debate oversimplifies the trade-offs. In Ontario, the answer has to be tested against the 53.53% top marginal rate, the 2.2% small-business corporate rate effective July 1, 2026, and the passive-income rules that can strip away the small-business deduction when investment income inside the corporation gets too high.
What changes the answer
Salary is useful when you want RRSP room, a clearer personal income profile, and a straightforward compensation trail. Dividends work better when you want simplicity and do not need the same pension-style mechanics. Retained earnings can support working capital or future acquisitions, but only if you are not loading too much passive investment income into the corporation and weakening the low-rate advantage.
The passive-income rule is the part many owners miss. Once passive investment income exceeds $50,000 in a year, the Small Business Deduction is reduced by $5 for every $1 over the threshold. By $150,000 of adjusted aggregate investment income, the deduction is fully gone. That means the corporation can lose its low active-business rate precisely when the owner thought keeping cash inside was being prudent.
| Scenario | Corporate Active Income | Passive Income | SBD Status | Combined Tax Cost |
|---|---|---|---|---|
| Operating company with modest retained cash | Active income only | Below clawback level | Preserved | Lower than an eroded SBD structure |
| Operating company holding excess investments | Active income plus passive income | Above $50,000 threshold | Reduced or eliminated | Higher, because passive income hits both current and future rates |
| Owner pulls too much out personally | Active income only | Minimal | Preserved at corporate level | Personal tax rises sharply at higher brackets |
| Mixed salary and dividend mix | Active income plus planned withdrawals | Controlled | Preserved or partly preserved | Usually the most flexible, but only if modelled |
The right mix is a cash-flow decision, a family decision, and a business-structure decision at the same time. If the owner needs income now, the corporation may have to distribute more. If the goal is to preserve room for reinvestment or a future sale, the corporation may need a different mix and less passive buildup. That is the point of planning, model the trade-offs before the payout method is set.
Who Tax Planning Services Are Built For
The same framework works across different clients, but the pressure points are not the same. A one-size-fits-all checklist fails because an operating company, a professional corporation, and a family balance sheet don’t have the same tax problem.
The main client profiles
Owner-managers of operating companies need help with remuneration, passive income, and exit readiness. Their biggest risk is letting corporate cash, owner pay, and future sale planning drift apart.
High-net-worth families need coordination across accounts, trusts, and ownership structures. Their concern is less about one return and more about preserving optionality as the family situation changes.
Incorporated professionals face a different mix. Doctors, dentists, lawyers, engineers, and similar professionals often need a tighter read on compensation, spousal planning, and whether corporate assets are aligned with their long-term personal goals.
Real estate investors need to know whether properties belong personally, corporately, or in a holding structure, and how GST/HST, financing, and future disposition rules affect the answer.
If you’re unsure where you fit, a general personal tax accountant can be a starting point, but the true value appears when the filing picture is tied to ownership, transition, and cash-flow decisions.
The point isn’t that every client needs the same depth in every area. It’s that the right engagement should map directly to the decisions that are live on the table.
How a Year-Round Planning Engagement Actually Works
The cadence matters as much as the technical answer. If the firm only shows up in March, it’s already too late to influence the year that created the return.
A real engagement rhythm
The year should start with an annual strategy session. That’s where the owner and advisor set the compensation approach, dividend policy, and investment direction for the months ahead. The output should be a written compensation memo and a short list of decisions the owner needs to approve.
Mid-year, the file should reopen when something material changes. That could be an acquisition, a hiring move, a spouse joining the business, or a sale discussion. The advisor shouldn’t wait for filing season to react.
October and November are where year-end projection work earns its keep. That’s when the team pressure-tests the current-year numbers and locks in the final moves while there’s still time to act. If you want a useful benchmark on why this timing matters, see why year-end planning should start in September, not December.
Practical rule: year-end tax work should feel like decision support, not a scramble to document choices already made.
The spring review closes the loop. That post-filing conversation should compare what was planned versus what happened, then feed those lessons into the next cycle. Without that review, the same mistake gets repeated with a new date on it.
That’s also where the client should see the family income projection model, updated assumptions, and any unresolved questions. If the firm can’t show you what it thought would happen and what happened, it’s not managing the process. It’s just processing it.
Planning Around Transitions, Sales, and Estates
The biggest payoff in tax planning usually shows up when life changes, not when a return is filed. A business sale, estate freeze, separation, or succession event can make the wrong structure expensive very quickly.
When the stakes rise
Take a representative owner who is selling the operating company to a strategic buyer while the spouse holds real estate and the kids are nearing adulthood. If the shareholder agreement hasn’t been reviewed, the estate freeze hasn’t been refreshed, and the ownership picture hasn’t been mapped cleanly, the deal team is already working with a handicap.
That’s the moment when coordination matters across shareholder, trust, estate, and family planning. You want to know whether the shares qualify for the capital gains exemption, how liquidity will be created if something happens before closing, and whether the family has the right structures in place to preserve flexibility after the sale.
The same logic applies before an estate freeze, business sale, or shareholder separation. The question isn’t just what tax is owed. It’s what is owned, who can transfer what, and whether the numbers support the move before it becomes irreversible. Ontario’s temporary HST relief measures for qualifying new homes and rental housing make that sequencing even more relevant for families and investors thinking about property decisions as part of a broader transition, not a stand-alone filing event (Ontario budget 2026 coverage).
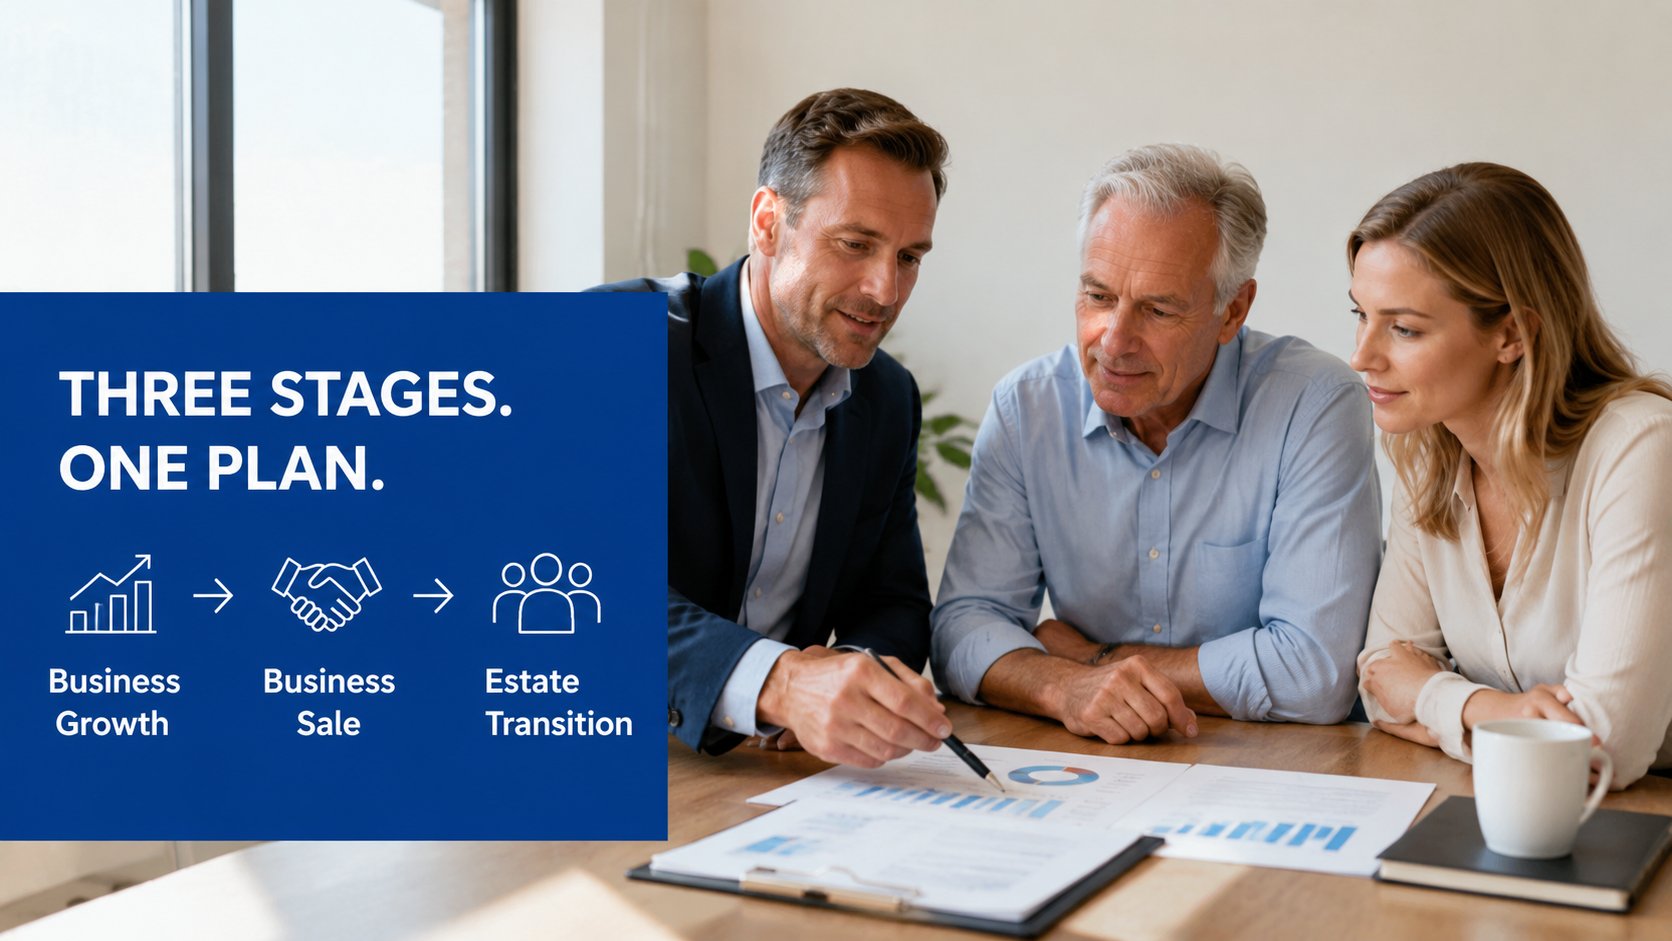
Fragmented advice tends to create avoidable friction, like attribution disputes, probate delays, or a deal structure that leaves too much value trapped in the wrong place. Coordinated planning is less dramatic, but it’s far more useful. It keeps options open until the last responsible moment.
Choosing a Firm and What to Expect
The right firm doesn’t just know tax rules. It can model the personal and corporate picture together, explain assumptions, and tell you what to do next quarter instead of hiding behind process language.
What to look for
You want a year-round cadence, not a March rush. You want written deliverables that show the logic, not just the answer. You also want an advisor who can speak confidently about the 2.2% small-business rate change, the passive-income clawback, and the practical trade-offs behind salary, dividends, and retained earnings.
Watch for warning signs too. If the fee only rewards deductions found, the incentive is backwards. If you never speak to the senior person who’s modelling the file, the work is probably being delegated too far. If the firm offers a generic checklist and calls it planning, keep looking.
A serious engagement should leave you with three things:
- A clear decision for this quarter.
- A short list of items to defer until facts change.
- A trigger list for when the plan should be revisited.
C&P Partners CPA works in that advisory-led lane for owner-managers and high-net-worth families in the GTA, with tax planning built around the decision in front of you rather than a filing calendar. If you want your tax work tied to compensation, structure, and transition decisions, visit C&P Partners CPA and ask for a planning conversation.